Tag

Construction

Browsing


Private residential construction spending rose in August 2026 following a series of declines during the second quarter of the year. According to the latest construction spending data from the U.S. Census Bureau, private residential construction spending came in at a seasonally adjusted annual rate (SAAR) of $882.3 billion in August, up 1.1% from July but down 4.8% from a year ago.

The increase in spending occurred across all residential sectors, with improvement (remodeling) spending posting the largest monthly gain at 2.5%. Over the year, however, remodeling spending was down 7.4%. Both spending on single-family and multifamily construction increased by 0.2% in August, but decreased 3.5% and 0.6% from a year ago, respectively. The decline in single-family construction spending is consistent with weak builder sentiment reflected in the NAHB/Wells Fargo Housing Market Index (HMI), amid rising interest rates and cost.

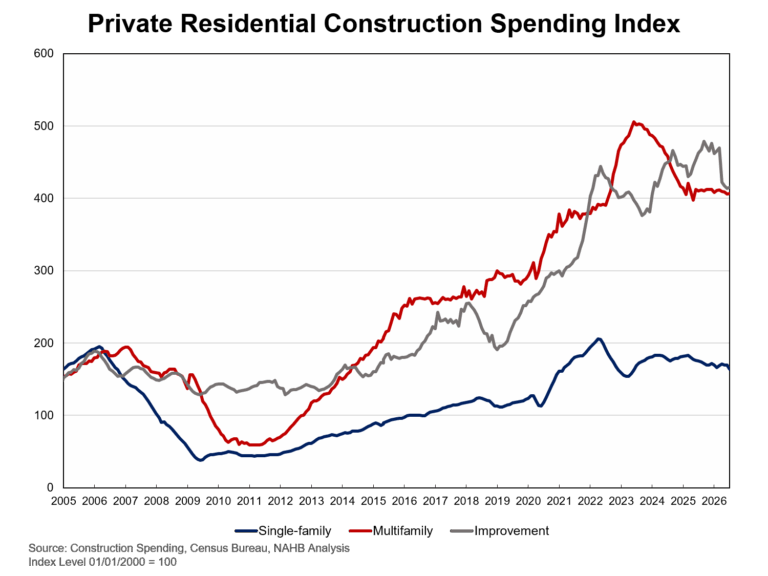
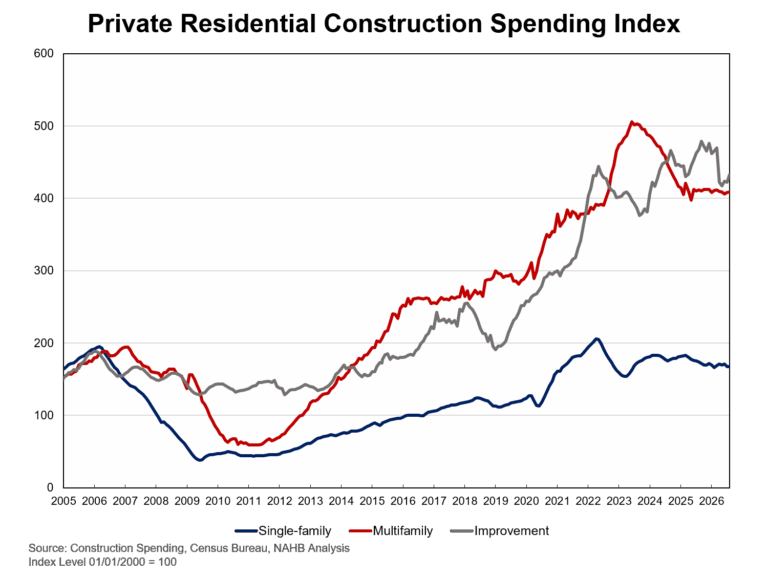
The NAHB construction spending index is shown in the graph below. The index illustrates how spending on single-family construction has slowed since early 2024, reflecting the impacts of elevated interest rates and ongoing uncertainty over building material tariffs. Multifamily construction spending growth has also slowed down after the peak in June 2023, with the index largely plateauing since late 2024.

In contrast, improvement spending has been on an upward trend since 2023, supported in part by the aging housing stock and sustained demand for renovation. However, the latest data is consistent with a 2026 soft patch for remodeling.

Private nonresidential construction spending continued its upward trend. August’s spending rose 1.0% to a SAAR of $773.0 billion, although it remained 1.0% below the previous year. Data center construction, a subcategory within office construction, remained strong with spending increasing 7.5% month-over-month and 73.2% year-over-year, due to buildout of artificial intelligence infrastructure. The share of data centers as a percentage of spending on total private nonresidential construction surpassed 10% in July 2026.


This article was originally published by a eyeonhousing.org . Read the Original article here. .
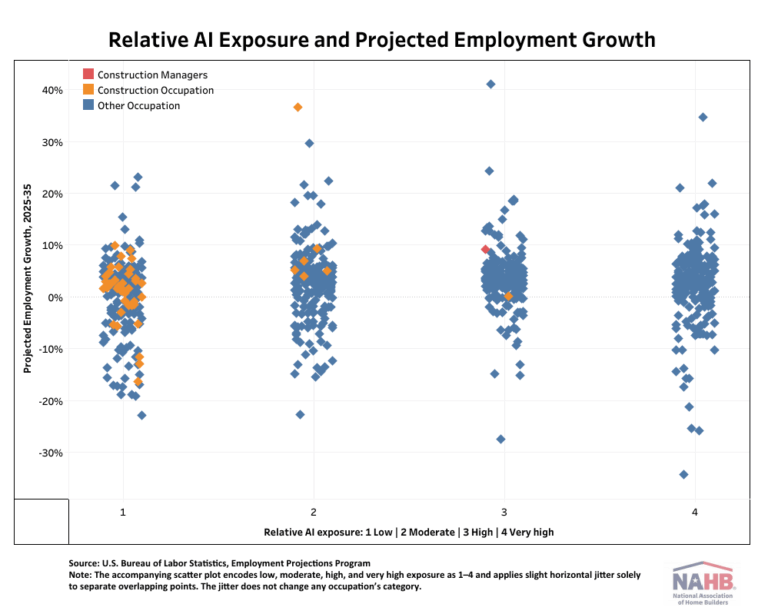

Artificial intelligence (AI) is rapidly changing how work gets done, but its impact varies considerably across occupations. For most construction occupations, near-term exposure to AI remains relatively low. An NAHB analysis of U.S. Bureau of Labor Statistics (BLS) data finds that 45 of 47 selected construction-related occupations—or about 96%—are classified as having “low” or “moderate” relative AI exposure. Only two occupations are classified as having “high” exposure, and none are classified as “very high”. These findings suggest that although AI is likely to change how construction work is performed, its current iteration has a less direct impact on many of the industry’s frontline occupations.

The chart compares relative AI exposure with projected employment growth from 2025 to 2035, illustrating that greater AI exposure does not necessarily correspond to faster or slower employment growth. Among construction occupations, construction managers and construction and building inspectors are the only two classified as having high relative AI exposure. Employment for these occupations is projected to grow 9% and remain essentially unchanged, respectively, from 2025 to 2035. By contrast, employment for solar photovoltaic installers, classified as having moderate exposure, is projected to grow 37%, making it the fastest-growing construction occupation in the group.

Among the selected construction occupations, the low-exposure group includes many hands-on trades and field roles, such as carpenters, construction laborers, roofers, and operating engineers. These jobs rely heavily on physical execution, changing jobsite conditions, safety judgment, coordination with other trades, and interaction with materials and equipment. These characteristics limit the direct reach of current software-based AI into many of the tasks performed in these roles. By contrast, construction managers and construction and building inspectors are classified as high-exposure exceptions, reflecting the greater role of planning, documentation, scheduling, compliance, reporting, and communication in these occupations. This distinction is consistent with findings from NAHB’s Housing Market Index (HMI) special questions, which show that builders primarily use AI for information-intensive tasks such as advertising and marketing, project planning, and project design. These findings complement the occupation-level AI exposure classifications, highlighting the greater applicability of AI to information-intensive functions than to hands-on construction activities.

Relatively low current AI exposure does not mean that construction is insulated from technological change. Instead, AI adoption may initially augment existing work through faster estimating and planning, improved document management, safety analysis, progress monitoring, and decision support. Changes to field operations may emerge more gradually through AI-enabled equipment, robotics, and computer vision. Recent findings from NAHB’s Housing Market Index (HMI) special questions show that builders identified technological advances as a positive long-term force for the housing industry.

Source:

U.S. Bureau of Labor Statistics, Employment Projections Program, “AI Exposure Categories and Employment Projections, 2025–35,” with definitions and limitations documented in the workbook’s Field Descriptions tab.

The BLS supplemental table, AI Exposure Categories and Employment Projections, 2025–35, combines five publicly available data sources to compare detailed occupations based on their theoretical and observed exposure to AI. The measure indicates whether AI technology could be, or has been, used to assist with or complete some tasks performed in an occupation. Importantly, it does not predict job losses, automation, productivity gains, or wage effects. This analysis focuses on 47 SOC construction occupations, excluding extraction occupations, plus construction managers. It does not represent the full workforce employed by construction firms, which also includes adjacent occupations such as architects, engineers, cost estimators, accountants, sales professionals, technology staff, and administrators. In addition, occupations are counted regardless of the industry in which workers are employed.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


The number of open positions in the construction sector fell back in August per the Bureau of Labor Statistics Job Openings and Labor Turnover Survey (JOLTS). The current level of open jobs is down from three years ago due to declines in construction activity, particularly in housing. Nonetheless, strength in construction for subsectors like data center construction (up 46% year-over-year) is creating demand for construction workers. Further, increasing immigration enforcement actions is having an effect on worker availability, which is also contributing to the number of open positions.

The number of open jobs for the overall economy fell back in August, declining to 7.08 million. The August reading was lower than a year ago (7.34 million). Despite the decline, national job openings remaining in the 7 million range indicates that the labor market remains resilient to recent macro challenges, including higher energy prices.

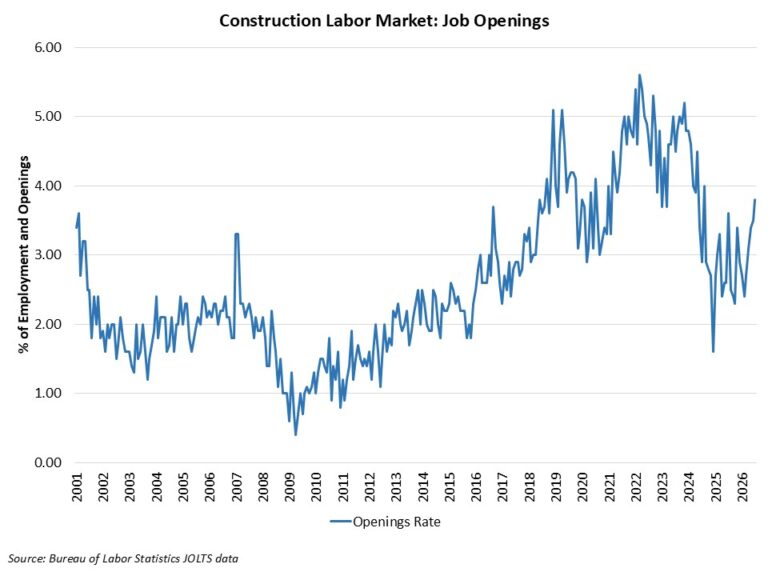
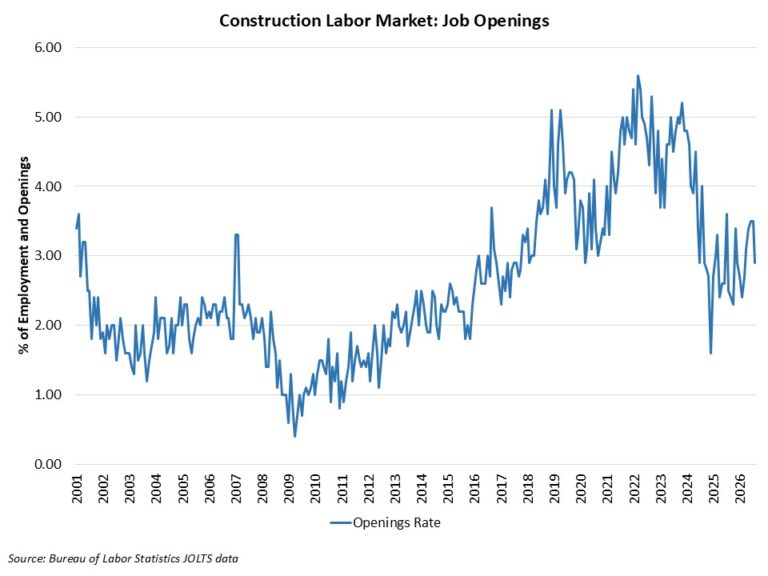
The number of open construction sector jobs declined for the month, decreasing slightly from 299,000 in July to 251,000 in August. This total is higher than the total from a year ago (213,000). The chart below notes a declining trend for the construction job openings rate from 2023 to 2025 (after Fed tightening monetary policy) to a recent rising trend for open positions in construction, albeit with significant month to month noise.

While home building employment has declined over the last year, other sectors of the construction industry have expanded (e.g. data center construction). The industry also faces challenges in terms of no shows at work sites related to immigration enforcement.

The construction job openings rate declined to 2.9% in August, but is up from 2.5% from a year ago.

The construction hiring rate declined to 3.7% in August, down from the 4.1% rate estimated a year ago.

The layoff rate in construction was lower at 1.3% in August. The quits rate was flat at 2.2%.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


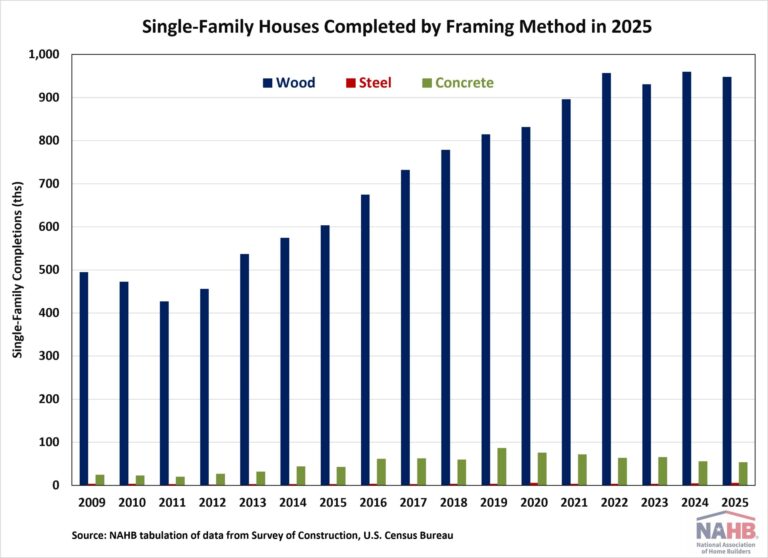
Wood framing continues to dominate the U.S. single-family home construction market, according to NAHB analysis of 2025 Census Bureau data. In 2025, wood framing accounted for 94% of all completed single-family homes, maintaining its position as the leading construction method. Concrete-framed homes represented 5% of completions, while steel-framed homes remained relatively rare, comprising half a percent of the market.

On a count basis, approximately 947,000 wood-framed homes were completed in 2025. This was a 1% decrease compared to the 2024 total. Despite the decline in the number of wood-framed homes, the wood-framed market share remained unchanged at 94% in 2025. Steel-framed homes, while still uncommon, continued to increase. About 5,000 steel-framed homes were completed in 2025, representing a 25% increase from the previous year.

Meanwhile, concrete-framed homes also experienced a decline. The concrete market share remained at 5% in 2025, while the number of concrete-framed homes completed fell to approximately 53,000, a 4% decrease compared to the prior year. Non-wood-based framing methods are primarily concentrated in the South due to residential resiliency requirements. In 2025, concrete-framed homes made up 9% of all single-family home completions in the South. Additionally, about 60% of all steel-framed homes completed in 2025 were built in the South, highlighting the region’s distinct building trends.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


In 2025, the number of women employed in the construction industry rose to around 1.37 million, an increase of about 31,000 from 2024. Women accounted for 11.3% of total construction employment, the highest share in the past 20 years.  

The growing presence of women in construction aligns with the expansion of white-collar jobs in the industry. As the industry continues to face a persistent shortage of skilled labor, expanding the workforce remains one of the top priorities of the industry. Increasing the participation of women into the construction labor force represents a potential opportunity for future growth. This article uses labor force statistics from the Current Population Survey (CPS) to examine the role of women in construction employment and the occupations in which women are most highly represented.

The number of women working in construction has increased substantially since the Great Recession. As shown in the figure below, the number of women working in construction declined from more than 1.1 million in 2007 to roughly 807,000 in 2010, as the housing recession sharply reduced construction activity. Since then, women’s employment in construction has generally trended upward. From 2010 to 2017, the number gradually rose to around 970,000 but remained below the peak of pre-recession levels. The number surpassed 1 million again in 2018, reached 1.24 million in 2021, and continued rising to 1.37 million in 2025.

The share of women in construction workforce has also increased. After remaining around 9% after the Great Recession, the share began picking up noticeably in 2017. By 2025, women represented 11.3% of the construction workforce, marking the highest share over the 2004-2025 period.

Although women’s share in construction workforce has increased, their participation in construction varies widely by occupations. According to the CPS data, most women are employed in occupations such as office and administrative support, management, and and business and financial operations. Women accounted for 78% of office and administrative support occupations within the construction industry, the highest share among major construction occupational groups. Women also represented 40% of workers in service occupations (excluding protective services), and 35% of workers in protective service occupations. Women also made up 24% of construction workers in professional occupations, 19% in sales occupations, and 16% in management, business, and financial operations occupations.

By contrast, women remained much less common in construction and maintenance occupations, which account for the largest number of employees in construction and are where additional workers are most needed. Women comprised only 4% of workers in construction and extraction occupations, 3% in installation, maintenance, and repair occupations, and 6% in production occupations. Increasing women’s participation in these occupations could help expand the pool of skilled workers available to the construction industry.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Building a new single-family home took less time in 2025 compared to the previous three years. On average, it now takes 8.8 months from start to finish. That time includes 1.4 months for authorization to start construction and another 7.4 months to finish construction.

Data from the Census Bureau’s Survey of Construction shows that single-family construction timelines have shortened as pandemic-era supply chain challenges have eased. However, the time period is still around 1.6 months longer than the average completion time in 2015. The longer construction timeline may reflect several headwinds facing builders, including a more stringent regulatory environment and an ongoing skilled labor shortage.

Among all single-family houses completed in 2025, homes built for sale required the shortest amount of time, 7.4 months from obtaining building permits to completion. Meanwhile, homes built by owners (portion of custom home building) required the longest time, 14.3 months. Homes built by hired contractors took about 11.7 months (the larger portion of custom home building), and homes built-for-rent required about 12.4 months from authorization to completion.

The chart below illustrates that permit-to-completion time differs across home sizes. The smallest single-family homes, under 1,200 sq. ft., required 12.2 months to finish, relatively longer than every other size homes except those over 5,000 sq. ft. This prolonged period is primarily because half of these smaller homes are constructed specifically for rental purposes, which typically takes longer building time from authorization.

In contrast, homes ranging from 1,200 to 3,999 sq. ft. are built at the average building time, typically around 9 months. As the size increases beyond 4,000 sq. ft., there is a noticeable upward trend in completion times. Homes of 4,000-4,999 sq. ft. take about 10.7 months, while those between 5,000- 5,999 sq. ft. extend to around 12 months. Homes over 6,000 sq. ft. take the longest to build, requiring 16.3 months from permit to finish.

The average time from authorization to completion also varies regionally across divisions. The division with the longest duration was New England (13.5 months), followed by the Middle Atlantic (12.6 months), the Pacific division (10.3 months), the East South Central division (9.1 months), and the Mountain division (9.1 months) in 2025. These five divisions exceeded the nation’s average of 8.8 months. The shortest period, 7.6 months, is registered in the South Atlantic division. The average waiting period from permit to construction start varies from the shortest time of 1 month in the East North Central and the West North Central to the longest of 1.8 months in New England.

The SOC also collects additional information for houses built for sale, including a sale date when buyers sign sale contracts or make a deposit. Looking at single-family homes built for sale and completed in 2025, 12.3% were sold before construction started, 29.3% sold while under construction, 18.5% sold during the month of completion, and 31.5% sold after completion. The share of completed houses remaining unsold was 8.3% at the point of survey. Compared with 2024, a larger share of new single-family homes remained on the market until after construction was completed. The share sold after completion rose from 27.0% to 31.5%, while the share sold while under construction fell from 33.0% to 29.3%, and the share sold before construction began declined from 15.2% to 12.3%. These shifts suggest that, despite shorter construction timelines, builders faced a weaker sales environment in 2025.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


The average time needed to complete construction of a multifamily building after obtaining authorization edged down in 2025, according to the 2025 Survey of Construction (SOC) from the Census Bureau. On average, it took 18.9 months from permit to completion, about 0.7 months shorter than in 2024. While construction timelines remain lengthy, this modest decline occurred despite the industry continuing to face a shortage of skilled labor.

Although multifamily construction time shortened in 2025, it remained lengthy compared to historical trends. The average time from permit to completion was still 3.5 months longer than the 15.4 months recorded in 2009 and almost 7 months longer than the period low of 12 months in 2013. Most of this long-term increase occurred during the construction phase. The average time from start to completion rose from 13.4 months in 2009 to 16.5 months in 2025, partly due to the growing share of larger multifamily buildings. The share of multifamily buildings with 50 units or more increased from 43% in 2009 to 57% in 2025, and larger buildings generally take longer to complete.

The average time to build multifamily homes varies with the number of units in the building. Despite the modest improvement for most building sizes in 2025, the construction times remained much longer than they were a decade earlier. In 2025, buildings with 20 or more units took the longest to build after obtaining authorization at 21.7 months, compared with 16.2 months in 2015 and 22.1 months in 2024. By contrast, 2-to-4-unit buildings were finished the fastest, averaging 14.9 months, up from 12 months in 2015 but slightly below 15.3 months in 2024. Mid-sized projects fell in between, with 10-to-19-unit buildings averaging 18.5 months in 2025, compared with 14 months in 2015 and 19.2 months in 2024, while buildings with 5-to-9-units averaged 21.5 months, up sharply from 13.2 months in 2015 and 19.1 months in 2024.

The 2025 SOC data also show a significant regional variation in the average construction duration of multifamily buildings. The Northeast had the longest time from authorization to completion at 21.9 months, followed by the West at 20.6 months, and then the South with 17.5 months. The shortest permit-to-completion period happened in the Midwest with 16.6 months.


This article was originally published by a eyeonhousing.org . Read the Original article here. .


Private residential construction spending fell further in July, marking its fourth consecutive monthly decline. According to the latest construction spending data from the U.S. Census Bureau, private residential construction spending stood at a seasonally adjusted annual rate (SAAR) of $859.0 billion in July, down 1.3% from the revised June estimate and down 7.3% from a year earlier.

The July decrease was driven entirely by the single-family construction, the only residential category to post a monthly decrease. Single-family construction spending fell 3.2%, consistent with the continued weakness in builder sentiment reflected in the NAHB/Wells Fargo Housing Market Index (HMI). On a yearly basis, single-family spending was down 6.5%.

Multifamily construction spending edged up by 0.2% from June but remained 0.9% below the previous year. Spending on improvement (remodeling) also saw a modest increase of 0.3% over the month but declined 10.2% over the year. The remodeling estimates, which had significant revisions in the June report, underwent further revisions in July. May’s monthly change was revised from a 0.4% decline to a 1.1% decline, while June’s initially reported a 0.1% increase was revised to a 0.8% decrease.

The NAHB construction spending index is shown in the graph below. The index illustrates how spending on single-family construction has slowed since early 2024, reflecting the impacts of elevated interest rates and ongoing uncertainty over building material tariffs. Multifamily construction spending growth has also slowed down after the peak in June 2023, with the index largely plateauing since late 2024.  In contrast, improvement spending has been on an upward trend since 2023, supported in part by the aging housing stock and sustained demand for renovation. However, the latest revision indicates that a slowdown could be happening in 2026.

Private nonresidential construction moved in the opposite direction, recording its fourth consecutive monthly increase. July’s spending rose 0.4% to a SAAR of $755.2 billion, although it remained 3.3% below the previous year. Data center construction, a subcategory within office construction, remained strong with spending increasing 6.2% month-over-month and 57.2% year-over-year. The share of data centers as a percentage of spending on office construction has now surpassed 60% in July 2026.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

The number of open positions in the construction sector increased in July per the Bureau of Labor Statistics Job Openings and Labor Turnover Survey (JOLTS). The current level of open jobs is down from three years ago due to declines in construction activity, particularly in housing. Nonetheless, strength in construction for subsectors like data center construction (up 46% year-over-year) is creating demand for construction workers. Further, increasing immigration enforcement actions is having an effect on worker availability, which is also contributing to the number of open positions.

The number of open jobs for the overall economy increased slightly in July, rising to 7.27 million. The July reading was higher than a year ago (7.09 million). The recent increase in job openings for the overall economy indicates that the labor market remained resilient during the summer, despite concerns over headline risk and AI.

The number of open construction sector jobs increased for the month, rising slightly from 298,000 in June to 326,000 in July. This total is also higher than the total from a year ago (305,000). The chart below notes a declining trend followed by a new range for unfilled construction jobs since the Fed raised the federal funds rate and home building weakened.

While home building employment has declined over the last year, other subsectors of the construction industry have expanded (e.g. data center construction). The July data suggest a breakout from the range for the last two years is possible given the crosswinds affecting the construction labor market.

The construction job openings rate increased to 3.8% in July, up from the 3.6% rate estimated a year ago.

Construction hiring picked up in July, with the hires rate rising from 3.8% to 4.4%.

The layoff rate in construction was flat at 1.9% in July. The quits rate increased to 2.3% in July.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

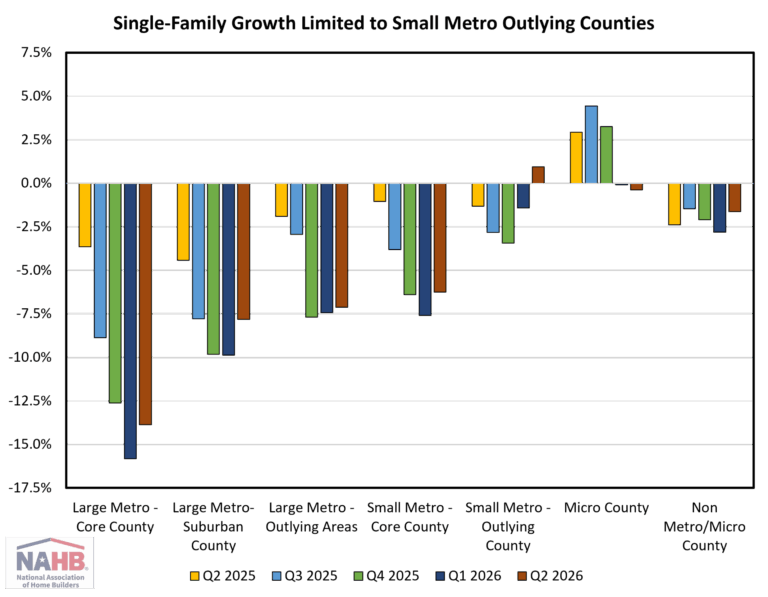
Home building trends diverged across geographies in the second quarter of 2026. According to the Home Building Geography Index (HBGI), single-family construction declined in nearly all geographic categories, although the contraction eased in most markets from the first quarter. Multifamily construction expanded across six of the seven categories, with activity increasingly concentrated in large metro core and suburban counties.

Single-Family

Single-family construction declined in six of the seven geographic categories in the second quarter. However, the downturn in single-family construction in the second quarter eased as these geographies contracted at a slower pace from the previous quarter.

Large metro core counties recorded the steepest decline, falling 13.9% and marking the fifth consecutive quarter of decline. This was an improvement from the 15.8% decline in the first quarter. Outlying counties in small metro areas were the only market to return to growth, increasing a modest 0.9% following four consecutive quarterly declines.

The geographic composition of single-family construction continued to shift toward smaller and less densely populated markets. Large metro core counties experienced the largest market share decline, falling 1.3 percentage points from a year earlier to reach another new low point at 14.6%. By contrast, small metro outlying counties posted the largest gain, increasing 0.8 percentage point to 10.9%.

Small metro core counties remained the largest single-family market, accounting for 29.4% of construction, followed by large metro suburban counties at 24.0%.

Multifamily

Multifamily construction expanded in all markets except large metro outlying counties. Large metro core counties increased 11.6%, recording three-quarters of consecutive growth. Compared to the previous quarter, the pace of increase has slowed but the market still recorded the strongest growth among all geographies.

Large metro suburban counties also followed a similar pattern, posting a 7.9% increase, although growth has slowed from the prior quarter. In contrast, large metro outlying counties declined 15.9% and were the only market that contracted for the multifamily sector.

Non-metro/micro counties posted the clearest acceleration, with growth rising to 10.3%, although these areas accounted for only 1.2% of multifamily construction.

Multifamily market share continued to shift toward large metropolitan areas. Large metro core counties gained 1.6 percentage points from a year earlier to reach 35.4%, while large metro suburban counties gained 0.5 percentage points to reach 27.3%. Together, these markets accounted for 62.7% of multifamily construction.

The second quarter of 2026 HBGI data along with an interactive HBGI map can be found at https://nahb.org/hbgi.


This article was originally published by a eyeonhousing.org . Read the Original article here. .

Pin It